Collections
Why collections WhatsApp numbers get banned — and how to reduce the risk
If a collections WhatsApp number got restricted, it was rarely one thing. In credit operations we see five causes, usually stacked: a use case Meta does not allow, numbers without consent, misclassified templates, context-free blasts, and running off the official stack.
Rotating the number fixes none of them. Below: how to tell which one is hitting you, and what to change.
WhatsApp works when you treat it as a conversation inside a case — not a channel for emptying a list.
Blast
Same template · whole list
- 10,000 accounts
- Same template
- More blocks and reports
- Quality drops
- Restriction
Stable health
Case-based
One case · voice + WhatsApp
- Book
- Segmentation
- Voice + WhatsApp
- Customer reply
- Case continues
- Stable quality
Stable health
Illustration. We do not invent Meta thresholds.
First: is your use case allowed?
Meta lists payment reminders and account alerts under Utility messages. Its WhatsApp Business policy also lists debt collection among restricted services.
A lender reminding a borrower about their own installment is not the same as an agency recovering a third party’s late-stage debt. And calling a template “Utility” does not make every collections action allowed.
Message category and use-case eligibility are two different questions. If you run third-party or late-stage collections, check the specific use case against current policy and local regulation before you scale.
Five layers of a healthy WhatsApp operation
- 01Permitted use case
- 02Consent
- 03Correct template
- 04Channel quality
- 05Operational orchestration
Each layer protects the next.
Cause #1: having the number is not consent
A phone number on a loan application does not authorize WhatsApp outreach. Policy requires that the person gave the number and explicit consent to receive WhatsApp messages from that business, with a clear way to opt out.
Bought, scraped, or third-party-enriched mobiles are reachable, not eligible. The result shows up fast: a message the person did not expect, from a number they do not know.
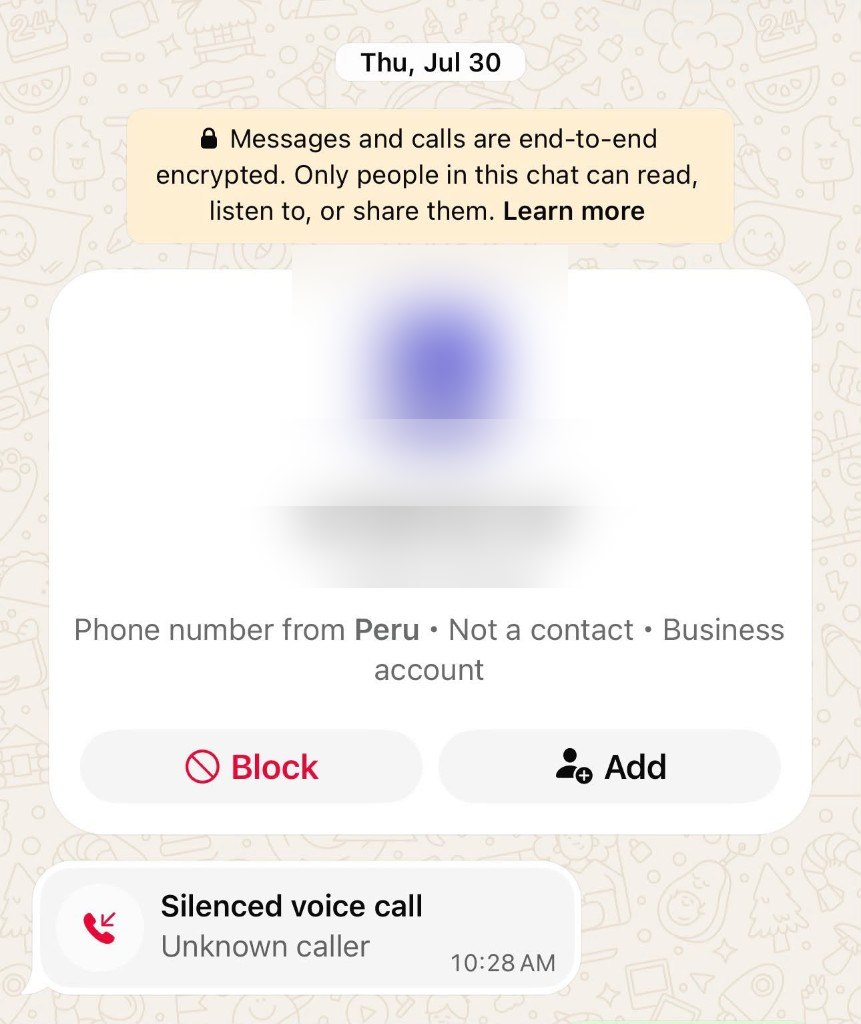
That Block tap is the signal that pulls the quality rating down. Meta can limit businesses that stay at low quality for a prolonged period.
What to check: where the number and the opt-in came from for each segment of the book. Anything without clear consent comes off WhatsApp, or gets asked for permission on another channel.
Cause #2: a campaign dressed as an account message
“Your installment is due 5 October” is an account notice. “Last chance, settle today” is a campaign. Meta reviews templates and can pause or reject them, so hunting for words that “trick” the classifier only delays the problem.
Utility
Hi Ana. Your S/240 installment is due 5 October. You can review your account details here.
Campaign / ambiguous
Ana, don’t miss this chance. Settle today and avoid problems.
Illustrative examples. Final classification is Meta’s.
What to check: could you explain why each template belongs in its category if Meta reviewed it tomorrow? If the answer is not obvious, rewrite it.
Cause #3: using WhatsApp as a blast
Volume alone is not the problem. Sending 50,000 messages on Monday without looking at what happened on each account is:
- Did this customer already get a call?
- Did they answer yesterday?
- Did they make a promise to pay?
- Did they ask to be contacted later?
- Did they already get another message?
- Did they reply on WhatsApp?
Meta can restrict businesses with too much negative feedback or unauthorized large-scale messaging. It does not publish a safe threshold — there is no “below X% you will never get banned.”
What to check: the trend, not a magic number. If blocks rise or the quality rating drops as you add volume, slow down and segment before you push further.
Cause #4: running off the official stack
A phone wired to a server, WhatsApp Web automation, or a vendor promising “unlimited” messages. It works until it doesn’t.
What to check: that you run on WhatsApp Business Platform, directly or through an official provider, and that the WABA, numbers, and templates are in your company’s name — not a third party’s.
Done right, WhatsApp performs for payment reminders
Meta publishes the Pegadaian case: a state financial institution in Indonesia that used automated Utility messages for payment reminders and account notices. From January 2023 to July 2024 it reported:
WhatsApp for payment reminders — case published by Meta
Source: Pegadaian / WhatsApp Business. Company-reported results; individual results may vary.
These are company-reported figures and not necessarily repeatable. What they show is that the channel works when the operation is designed for it.
Continue the case, don’t start over
A customer promises to pay on a 10:15 call. At 10:17 a disconnected system writes: “Hi, we’re contacting you because you have a payment due…”. They just spoke to you. An omnichannel operation sends something like: “Thanks for the call. As agreed, here are the details to pay tomorrow.”
Note: a phone call does not open the WhatsApp service window. You can reply freely for 24 hours from the user’s last WhatsApp message; outside that window you need an approved template.
One case, multiple channels
case_id · 4821
- 09:30Voice agent attempts contact → no answer
- 13:00WhatsApp Utility → reminder
- 13:07Customer replies
- 13:07+Service window open
- 18:00Customer promises to pay tomorrow
- +1dAgent checks the outcome and picks the next action
Coordinating voice and WhatsApp on one case also lowers risk. Not every action needs WhatsApp, and if all of collections hangs on thousands of outbound messages, any quality or policy change becomes an incident. Nobody can guarantee Meta will not restrict a number; a multichannel operation holds up better when it happens.
Single-channel
50K accounts → WhatsApp → high dependency / blast
Multichannel
50K accounts → PathPilot Agent → voice · WhatsApp · human. One case record.
One case. Multiple channels. One context.
How we do it at PathPilot
PathPilot was built by an AI team with prior experience at Meta. That shapes how we run the channel: not a hack to send more messages before a ban, but contact rules the account holder does not read as spam.
Fixed rules, one useful exception
The agent does not pick the channel in a vacuum. Campaigns have rules. It can open WhatsApp outside that cadence when the account holder asks for account or payment details — information they just requested, not a blast to the whole list.
To start the thread we always use a template. Once the user writes back, PathPilot replies in the normal window.
The client’s templates, plus a pre-approved set
Templates belong to the client. PathPilot also ships a predefined set already approved by Meta, so collections copy is not improvised.
The WABA and the numbers are the client’s. PathPilot operates on their account. We do not keep the asset.
Consent on the call when it is missing
If the book already has the number, the agent can contact. When WhatsApp needs an explicit yes, it asks on the voice call — a CRM mobile is not treated as forever-consent.
Bring the account holder to WhatsApp, not the other way around
Our agents promote inbound WhatsApp in their communications: they share the company’s WhatsApp contact on other channels, such as SMS or email, so the account holder writes in when they want to ask or pay.
When the user opens the conversation, the number is no longer a stranger, the 24-hour window opens for replies without a template, and the chance of a Block tap drops.
Voice or WhatsApp by job, not by blast
For delinquency / collections the usual order is voice first, then WhatsApp. For a payment reminder it is WhatsApp first, then voice.
When to write and how many open attempts come from an ML model, fed by an internal quality agent that watches account health — not only Meta’s rating. If the holder does not reply, PathPilot stops opening on WhatsApp and moves to voice.
Campaigns come from the book. That book updates with the agent’s result and with changes the client adds. A promise to pay is not a one-off if: it changes account state, and the next contact follows.
The goal is not to maximize messages sent. It is to reduce restriction risk and not depend on one channel. UnoMotors and Refermat already run voice and WhatsApp this way.
Blast
Same template · whole list
- 10,000 accounts
- Same template
- More blocks and reports
- Quality drops
- Restriction
Stable health
PathPilot
One case · voice + WhatsApp
- Case priority
- Voice / WhatsApp
- Customer reply
- Next best action
- Stable health
Stable health
Illustration. We do not invent Meta thresholds.
What to measure on WhatsApp for credit
Do not wait for a ban to decide whether the operation is working.
A ban is a late signal.
The dashboard should connect channel health to business outcome: quality rating and its trend, template status, delivery and read rates, available block reasons, opt-outs and book eligibility; then operational metrics such as effective contact, promises to pay, kept promises, recovery, and cost per result.
The point is to answer a question that usually sits across teams:
Are we recovering more without damaging the channel we use to do it?
WhatsApp Health + Collections Outcomes
DEMOChannel health
Collections
Segments
Demo mock. Not a customer’s metrics.
A ban is not fixed by buying another number
When a line starts to deteriorate, the easy move is to rotate the number.
That does not fix the problem if the operation stays the same.
If the cause is consent, change consent.
If the cause is content, change the message.
If the cause is a bad contact strategy, change the strategy.
If the use case is not allowed, change the use case.
And if all collections depend on WhatsApp, change the architecture.
The right question is not:
“How do we stop Meta from banning us?”
It is:
“How do we build an operation customers expect, that meets the channel’s rules, and that still works if one channel changes?”
That is where a truly omnichannel collections strategy starts.
Keep reading
- WhatsApp collections cost (ES, soon EN)
- Voice AI collections and governance
- AI agents for collections
- Versión en español
Questions
Does Meta ban collections companies on purpose?
That is too simple. WhatsApp explicitly allows certain payment reminders and account messages as Utility, and publishes financial institutions that use them. At the same time, its Business Messaging Policy lists debt collection among certain restricted services. Evaluate the concrete use case. Do not assume every collections activity is equally allowed or forbidden.
Is having the customer’s phone enough to write them on WhatsApp?
No. WhatsApp requires that the user provided the number and gave explicit consent to receive later WhatsApp messages from that business.
What is the quality rating?
A signal of the experience people have with the business on WhatsApp. Meta uses user feedback, including blocks and reports, plus other signals it does not fully publish. Watch its trend together with delivery, templates, opt-outs, and operational results — not a secret formula.
Does a phone call open the 24-hour WhatsApp window?
No. The 24-hour service window is counted from the last message the user sent on WhatsApp. A call can add context to the case. It does not open that window.
So should we avoid WhatsApp for collections?
Not necessarily. For eligible communications, WhatsApp can be a high-engagement channel. Meta’s Pegadaian case shows the potential of correctly implemented payment reminders. The right strategy is not to depend on it alone. A multichannel architecture uses voice, WhatsApp, and human escalation by case state.
See a multichannel collections demo
Voice and WhatsApp on the same case. Open the demo or take 20 minutes.